
 |
Why Interest Rate is Lower on Savings than Loans It is often asked why interest rates are always higher for borrowers than for savers. This article explains some of the factors used to set interest rates. |
 |
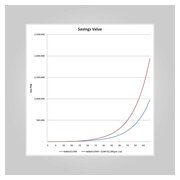
Smart Money Management: Why Small Interest Rate Changes Matter The investor needs to understand how a small difference in interest rate on long term savings makes a big difference to investment fund final performance. Savers should closely monitor the performance of their savings as a small change in interest rate or investment return can have a major effect over the long term. So for pension investment the smart investor will seek to maximise interest rate as long as she can do so without incurring excessive penalties to switch between savings accounts or funds. |
 |
Why Compound Interest on Debts Causes Problems Compound interest may help savers, and lenders, but it is the enemy of those in debt. This article shows why high interest rates often make borrowings unmanageable. |
 |
Use Credit Cards Wisely to Avoid Debt Problems Credit and store cards are a very easy source of credit but they are also very expensive. It is therefore not surprising their careless use cause so many debt problems. |
 |
Manage Borrowing and Credit Cards Effectively There are a few simple disciplines for managing borrowing so it does not get out of control and to make it serve the borrower rather than the lender. To control debt and borrowing it is more important to consider the term of loans rather than seek to minimise monthly repayments. |
 |
How to Avoid Debt Problems, Match Loan Period to Purchase Life
|
 Loan Period Wisdom for Reduced Debts